Rising interest rates, inflation push housing out of reach, says solon
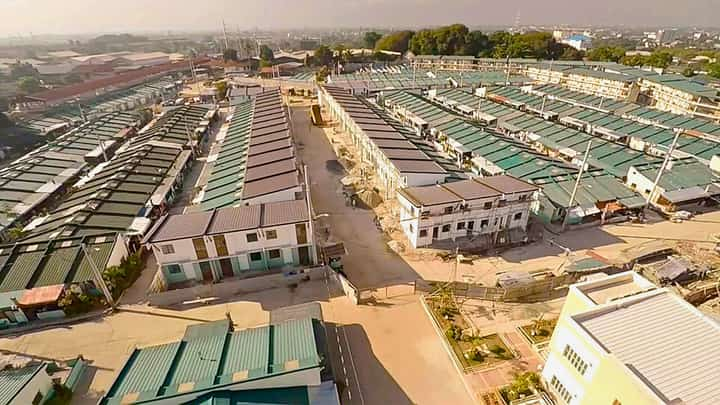
A recent 50-basis-point interest rate hike by the Bangko Sentral ng Pilipinas (BSP) to 5.50% could further push homeownership out of reach for Filipino families as credit terms tighten amid growing risks of stagflation, a lawmaker warned Monday.
Representative JP Padiernos, a member of the House Committee on Banks and Financial Intermediaries, said higher borrowing costs add severe pressure to an already struggling residential property market.
The warning comes amid concerns over slowing economic growth and persistent inflation, which threaten to constrain household purchasing power and housing finance access.
S&P Global Ratings recently highlighted a worsening macroeconomic backdrop for the country, pointing to a sharp slowdown in first-half gross domestic product (GDP) growth to 2.6%. Meanwhile, October inflation surged to a near four-year high of 7.8%.
The credit rating agency projects full-year 2026 GDP growth to reach a modest 2.9%, with annual inflation averaging 5.5%.
With high oil prices and a strong El Niño pattern expected to drive food costs higher, S&P anticipates weaker consumer spending and squeezed household budgets through the first half of 2027. Consequently, the central bank is expected to keep interest rates elevated to curb persistent price pressures.
"For families planning to buy a house or condominium through a bank loan, the BSP’s rate decision raises serious concerns about affordability, particularly as stagflationary pressures, rising food, electricity, fuel, and transportation costs,continue to erode household purchasing power," Padiernos said.
While benchmark policy rates do not trigger identical, immediate increases across all commercial housing loans,Padiernos noted they directly influence banks' underlying lending costs and repricing schedules.
"The BSP has an important role in maintaining price stability, which is essential to protecting the purchasing power of Filipino families. At the same time, we must examine complementary measures to ensure that higher borrowing costs do not further limit access to affordable housing," he said.
The pressure on domestic real estate demand was evident prior to the latest monetary tightening.
Data from Colliers Philippines showed that net take-up of Metro Manila condominiums dropped to 500 units in the second quarter of 2026—a 60% decline from the previous quarter and the lowest quarterly performance in five quarters.
Colliers also reported a clear shift toward lower-priced inventory. Condominiums priced between P1.8 million and P3.6 million accounted for 67% of total net take-up in the first half of 2026, up from 33% during the same period last year.
To navigate the high-interest and high-inflation environment, Colliers urged property developers to re-evaluate selling strategies and offer flexible, extended payment arrangements for residential units priced between P2.5 million and P12 million.
Padiernos called on financial institutions and government policymakers to develop targeted, accessible housing finance programs for middle- and lower-income first-time buyers to cushion the impact of prolonged monetary tightening.
He added that policymakers should explore targeted financial assistance, more flexible loan terms, and stronger coordination among government agencies, housing finance institutions, and private developers.
These measures, he stressed, should align with the actual financing capacity of prospective homebuyers to keep monthly amortizations manageable.