
Revisiting Hong Kong and remembering

Text size
For most of us who have been around for a few decades, meaning a senior citizen with lots of gray hair like yours truly, Hong Kong was, and probably still is because of its proximity, the go-to destination for a quick weekend getaway. And so it was for me and my fellow nomad travel partner, driven by the allure of yummy Cantonese cuisine and some shopping.
Hong Kong is a city that never stands still, and it never quite lets go of those who once lived in its restless embrace. Revisiting Hong Kong is always memorable for me because I lived in this former British colony during my expatriate days from the late 1970s to the early ’80s, which were halcyon years of deal-making and volatility as it transitioned from a British colony to an uncertain future with the handover back to China on 1 July 1997 as a Special Administrative Region under “One Country, Two Systems.”
This enabled the city to continue practicing capitalism with some degree of political freedom not possible in mainland China for a period of 30 years, with only foreign affairs and defense specifically reserved for the central government in Beijing.
Living and working in this vibrant city, which thrived on investment banking deals, either for the colony’s booming property market or for syndicated deals around the region in cities that were usually never more than an hour or two away by plane, was a dream come true for an eager-beaver investment banker.
Prior to the handover, corporate finance deals were being chased left and right, primarily centered on property development financing, which had property values skyrocketing based simply on blueprints even before the shovels broke ground. In hindsight, it was a classic bubble percolating and ready to burst.
And burst it did, shortly after the United Kingdom’s Iron Lady Prime Minister Margaret Thatcher’s visit on 24 September 1982 to then-China supremo Deng Xiaoping to negotiate the future of the colony.
When word got around the colony’s business and financial circles that Deng was firm in China’s position that “Hong Kong’s sovereignty is not negotiable,” panic set in, and inflated property values started dropping like a rock.
Lenders found themselves underwater in terms of seemingly safe loan covers for valuable properties, while business partnerships were on edge as the colony uneasily awaited how the Special Administrative Region would be administered going forward.
The most dramatic and cautionary tale for any investment banker and naive business group was the fallout risk of doing deals with a high-flying conglomerate riding the coattails of property speculation: the Carrian Group, which by 1982 controlled over 200 subsidiaries across Asia and the United States in shipping, hotels, insurance and finance. On the surface, it seemed to be a good bet to lend to or partner with, given its hedged, diversified holdings.
Carrian’s listed shares, which peaked at $17.90 per share, fueled frenzied investor interest and provided fodder for more leveraged financing against share values and even unsecured lending.
The most spectacular and scandalous of all deals were the massive loans extended by a Hong Kong investment bank subsidiary of a large Malaysian state bank, which led to the murder of an internal auditor of the state bank and eventually the imprisonment of several personalities involved in the Carrian transactions.
The business and international financial community was abuzz with speculation as to the mysterious source of seemingly endless funding for Carrian’s ability to do spectacular deals, the most dramatic being the purchase of the Gammon House high-rise building in the heart of the Central District, which Carrian purchased for about HK$1 billion in January 1980 and flipped by October for HK$1.68 billion — a transaction later determined to be riddled with deeply concealed fraud.
When Carrian finally collapsed in 1983 under the weight of massive leverage and deflated collateral valuations, the colony’s financial community was left holding the bag for HK$7 billion in creditor losses. Ironically, as it turned out, it was the reckless and imprudent lending practices of the banks chasing deals that fueled Carrian, prompting tighter supervisory oversight by banking regulators in its aftermath.
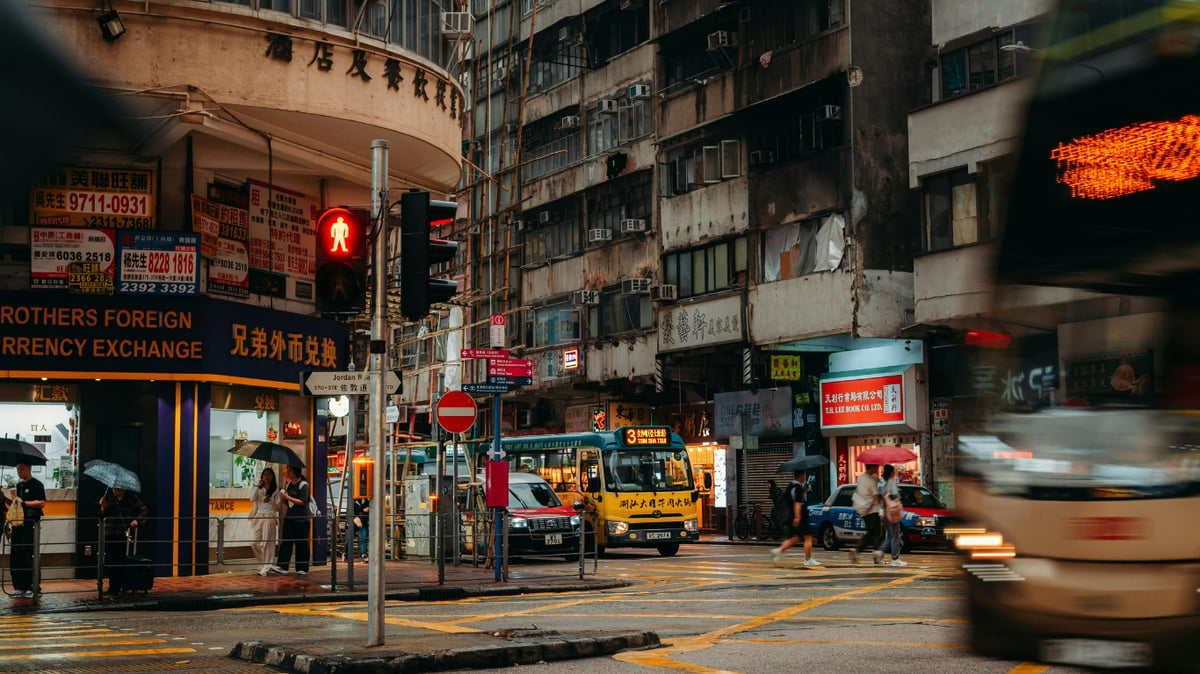
Today, the ugly memories and long-forgotten lessons of the past have long faded into history as gleaming super skyscrapers dominate the skyline of Hong Kong and the New Territories.
Business is humming with AI-related electronics exports, financial services, logistics and inbound tourism. Hong Kong International Airport is the world’s busiest cargo gateway and one of the largest passenger terminals and busiest airports in the world. Glitzy luxury malls and teeming street markets dotting Tsim Sha Tsui, Central, Harbour City, Causeway and Mong Kok continue to beckon hordes of tourists and shoppers.
Amid all the modernity of today’s Hong Kong, for sentimentalists like myself, during our weekend getaway, I still relished the old-fashioned 10-minute Star Ferry ride across Victoria Harbour, particularly at night, with the glittering lights of the Avenue of the Stars in the background underlining the never-ending magic of Hong Kong.
Until next week… OBF!
For comments, email bing_matoto@yahoo.com.