
Keeping it in family

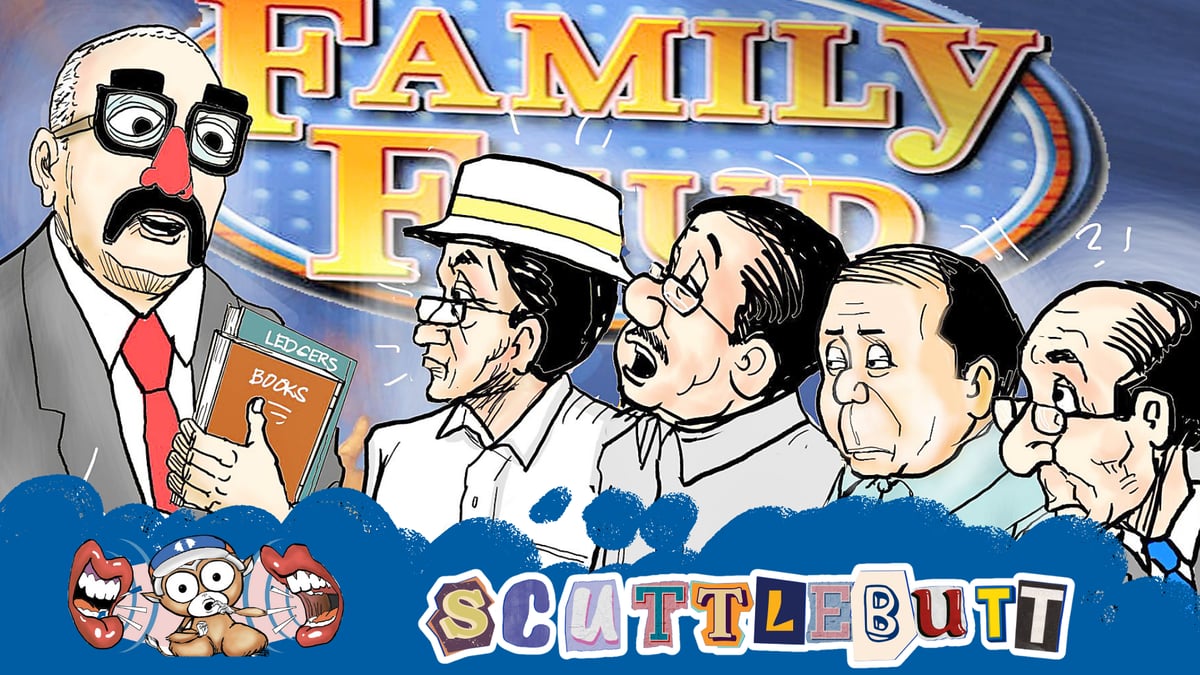
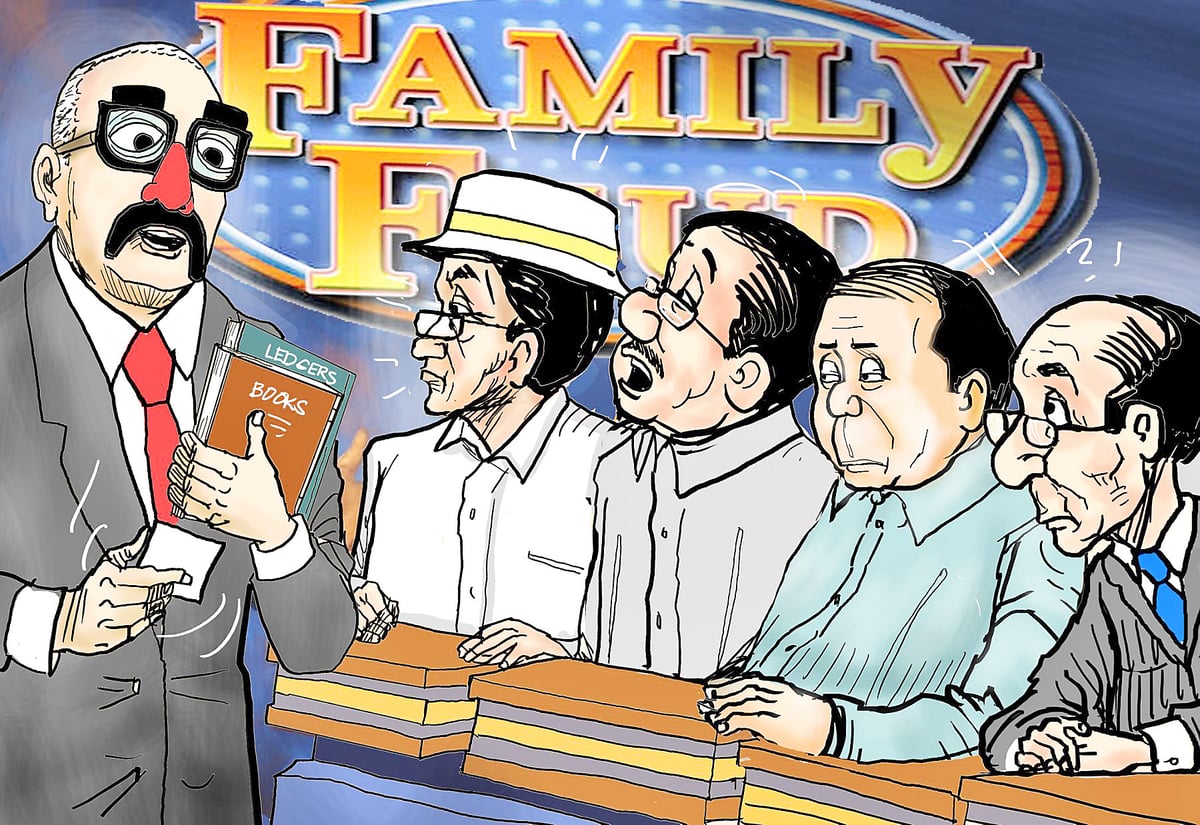
They held the meeting fast, right after the stockholders left the room, the way families do things when they don’t want an audience lingering. The old holding company, the one built on power and broadcasting and blood that doesn’t dilute after four generations, kept it in the family.
The chairman stayed chairman. The vice chairman is a brother. The president, who also runs finance, is another brother. The treasurer, who also handles corporate affairs, again a brother. Four surnames, one surname, running a listed company answerable to thousands of strangers who bought shares on a ticker.
But upstream, above the listed company, something had already moved. A cousin’s branch, the one that used to run the broadcaster before Congress killed its franchise, sold out. Sold to a tycoon who already owns a beer empire, a cement plant, an airline stake, and now roughly a quarter of that private company that sits on top of it all.
He called himself a friend to every branch of the family. He was told the shares “weren’t for sale” when he asked about the rest. He is, by his own account, just a steady hand at the table.
That steady hand doesn’t sit on the listed company’s board yet. His quarter-share lives one floor up, in the unlisted parent, alongside three other family branches that still hold the wheel. For now.
Here’s the arithmetic worth sitting with. The parent owns better than four-fifths of the listed company’s stock.
The family bloc, by every account, voted the way management wanted on reappointing its longtime external auditor.
So the 416,953,152 shares that voted no — more than ten percent of the total, and originally filed away as harmless abstentions before somebody had to correct the record — didn’t come from upstairs. They came from the free float. From the public. From the strangers.
The tycoon’s arrival didn’t cause that revolt; his stake sits too far upstream to have cast those votes. But it didn’t happen in a vacuum either.
A family feud fierce enough to send one branch running for an outside buyer is exactly the kind that makes outside shareholders start asking who’s really watching the books.