Futile BSP formula
When loans become costlier, households borrow less, and businesses slash investments.
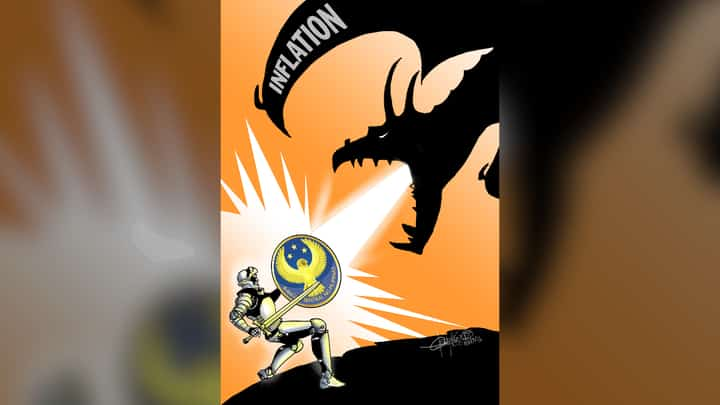
The Bangko Sentral ng Pilipinas (BSP) appears to be fighting a losing battle against inflation and the weakening peso.
On Wednesday, the currency closed at P63.25 to the US dollar, weaker by 34 centavos from Tuesday’s P62.91. Stronger-than-expected US inflation data fueled demand for the greenback, pushing the peso back into P63 territory. Only last week, it plunged to a record low of P64.17.
The BSP just raised interest rates by 50 basis points, or half a percentage point, to contain inflationary pressures and support the peso. Yet the currency continues to weaken, raising questions about how much more monetary tightening can achieve against external pressures.
An interest rate hike is a simple lever. When loans become costlier, households borrow less and businesses slash investments. With less money chasing goods, prices should ease.
Economists call this demand-side inflation, and rate hikes are well suited to it.
Not all inflation comes from too much spending. Sometimes prices rise because the cost of producing or importing goods has climbed. This is supply-side inflation. A higher interest rate does nothing to lower the price of a barrel of oil.
Sonny Africa, executive director of think tank IBON Foundation, argues that the inflation surge is mostly a supply problem. Oil and other imports have grown more expensive since the unwarranted US attack on Iran.
The BSP is treating a fever with a cure meant for a different illness, and it is having severe side effects. Higher borrowing costs squeeze families and small businesses. Budgets tighten, spending falls, and growth slows, all without addressing the real sources of inflation.
The timing makes this harder to defend. The Gross Domestic Product (GDP) grew by only 2.3 percent in the second quarter. In September, 307,000 fewer Filipinos were employed than a year earlier. The national average nominal minimum wage is P518 a day, while Ibon estimates that a family of five needs P1,319 a day for its food and non-food needs. That leaves a gap of about P800.
Demand is already weak because prices are high and incomes are low. People are spending only on bare necessities. Raising the cost of credit on such an economy risks pushing it further down, according to the economist.
The currency adds another layer. A weak peso makes every import costlier, including fuel, machinery, and raw materials. Costlier imports raise prices at home. Higher prices erode confidence, pushing the peso lower still. It is a vicious loop, and a rate hike alone does not break it.
President Ferdinand Marcos Jr. urged calm, telling the public not to panic, while blaming the peso slide on rising oil prices from the US-Iran conflict. He pointed to the country’s healthy gross international reserves as a cushion that can help steady the currency.
Former BSP Deputy Governor Diwa Guinigundo offers a harder diagnosis. In his view, fundamentals have weakened the peso. The balance of payments has been negative for months and years, meaning more dollars leave the country than enter it.
Investors who lose confidence move their money out. He said some banks have seen clients buy dollars with pesos to send abroad.
The persistent political noise feeds the worry, as investors become jittery and ask whether the country has strong political and economic institutions. Speculation that the US Federal Reserve may raise rates, given high US inflation, is also pulling money toward the dollar.
Oil is outside the BSP’s control. So are the Fed, the Middle East, and investor sentiment about governance. The central bank is fighting forces that its tools can barely touch.
Africa noted that higher rates affect borrowing and investment almost at once. The wider damage to consumption, jobs, incomes, and growth will likely manifest over the next two to four quarters. Add the risk of a Super El Niño and what he calls inadequate government support for agriculture, industry, jobs, and purchasing power, and 2027 could be tougher still.
The BSP must publicly disclose how much of the current inflation it attributes to excess demand, rising production and import costs, and domestic market structures. It should also explain how each interest rate hike addresses these pressures without unnecessarily choking economic activity, as it has in Africa.
A tool is useful only when it works against the problem. The BSP is wielding a demand-cooling instrument against inflation driven largely by expensive oil and imports, even as investors pull away and the peso continues to slide. This is why critics describe the policy as a losing battle.
Malacañang says there is no cause for alarm. But the numbers tell a different story, as do families struggling to make ends meet on a meager P518 a day.
False reassurances from the Palace do not comfort them.