
Wrong tool for right problem
The tension between that resilience and the grim headline numbers traces back to one source – oil.

Text size
The tension between that resilience and the grim headline numbers traces back to one source – oil.


The Philippine economy in the last quarter of 2026 is a study in contradictions.
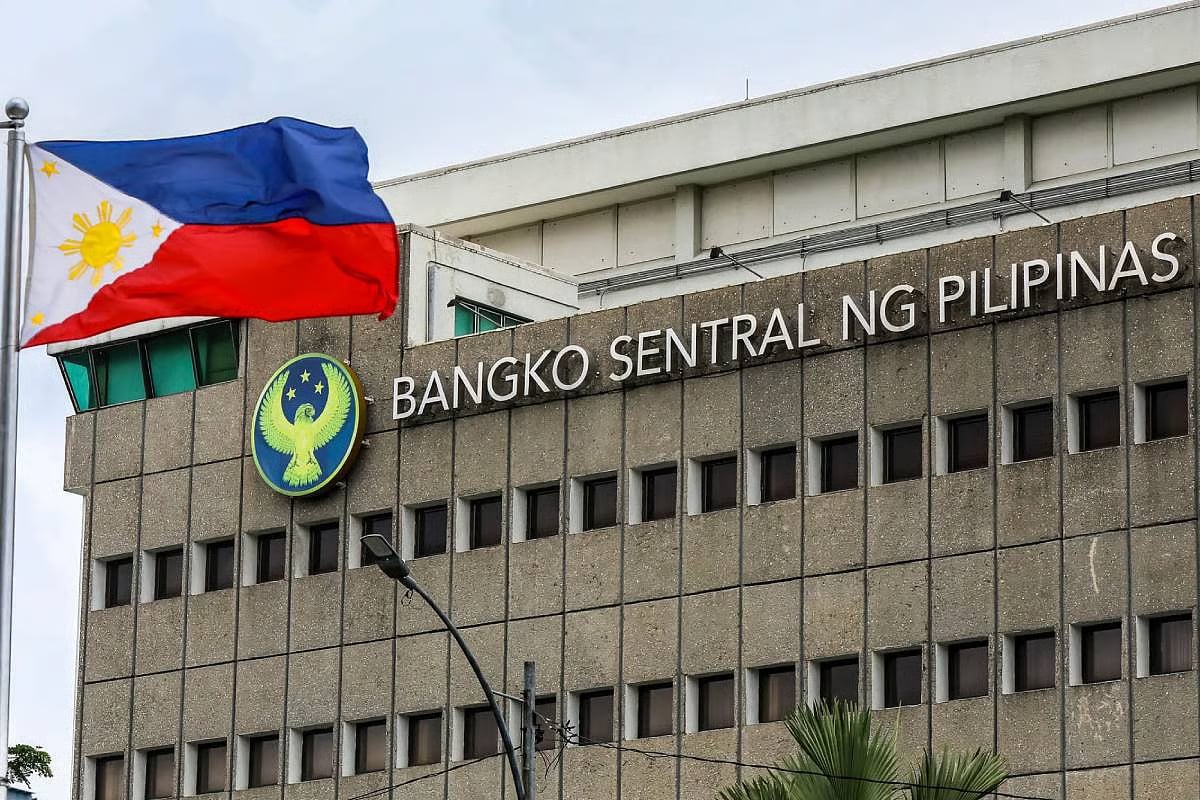
Headline numbers look grim. Inflation has stayed stubbornly above the Bangko Sentral ng Pilipinas’ two to four percent target for most of the year. The peso slid past sixty-one pesos to the dollar in August, a record low. Gross domestic product growth has come in below what analysts expected. And yet the capital markets, the part of the economy that is supposed to be most sensitive to this kind of bad news, are telling a different story.
The exodus of foreign investors is not a uniquely Philippine problem. Selling has hit nearly every market in Asia this year, with only a handful of exceptions. On a percentage of market capitalization basis, the Philippines has actually fared better than most of its neighbors.
Debt issuance on the Philippine Dealing and Exchange Corp. has already outpaced all of 2025, driven in part by a Securities and Exchange Commission circular that made private placements faster to execute. Delistings remain rare compared to other ASEAN exchanges, and the pipeline for 2026 includes the country’s first data center real estate investment trust and what could be the largest initial public offering in Philippine history, the listing of GCash operator Mynt Inc.
The tension between that resilience and the grim headline numbers traces back to one source — oil.
A Middle East-driven spike in crude prices pushed the Philippines, one of the region’s most import dependent economies for energy, into a familiar and painful cycle. Higher oil prices widened the trade deficit and weakened the peso. A weaker peso then made the same barrel of oil more expensive in local currency, feeding straight back into inflation.
The Bangko Sentral has raised its policy rate three times this year to five percent, and as of this writing was weighing whether an unscheduled hike was needed in response to expected tightening by the United States Federal Reserve, whose own ten-year Treasury yield has climbed toward its highest level since 2023. Rising American rates makes the peso less attractive to hold relative to the dollar, adding pressure on top of the oil shock rather than causing it outright.
This is the backdrop against which calls to raise the minimum wage deserve a careful look rather than a reflexive yes. Although the subject of a temporary restraining order, the National Capital Region has already moved its daily minimum wage higher, with another increase due in 2027, and the impulse behind it is fair.
Low income households spend a larger share of what they earn on fuel and food, so they absorb more of an oil-driven inflation shock than anyone else. But the central bank has named wage adjustments as one of the very risks it is trying to contain, worried about a cycle where higher wages push prices up further.
A blanket wage increase risks doing what higher interest rates are already trying to prevent. Targeted relief, in the form of transport subsidies or direct cash transfers, may protect the same households without feeding the inflation problem it is meant to solve.