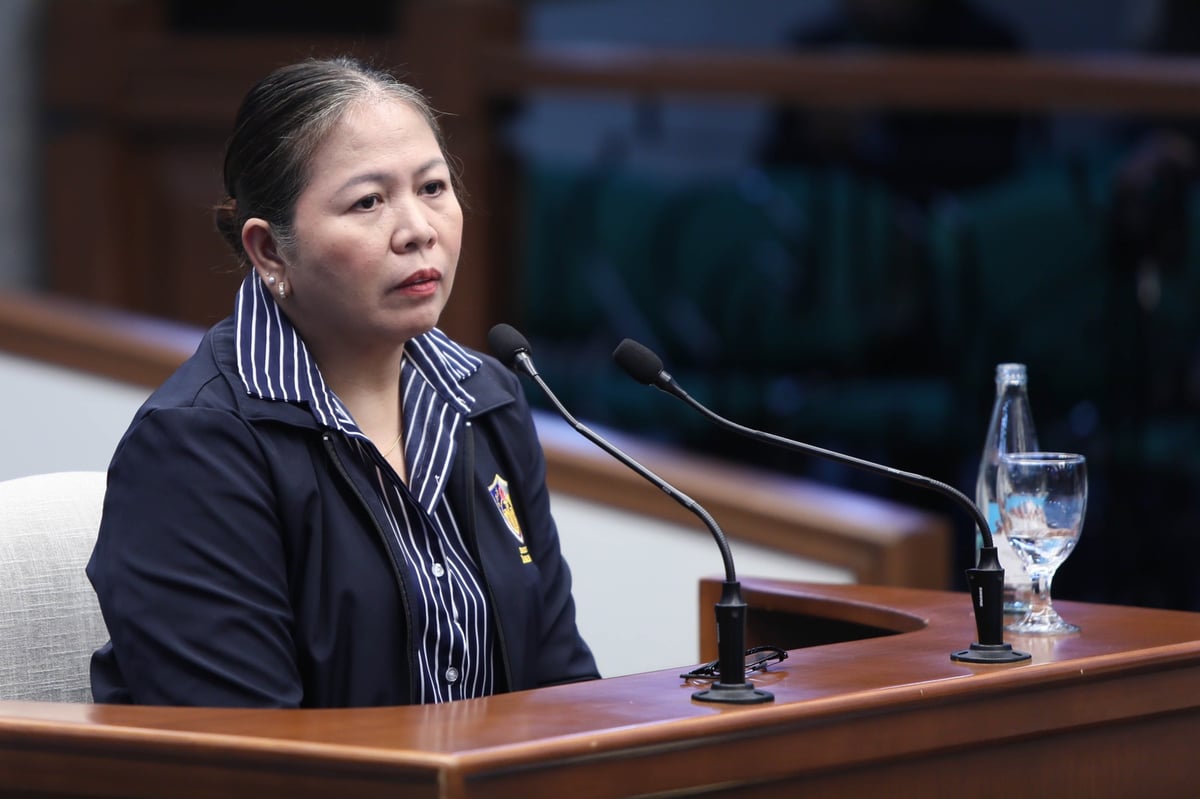
“2013 and 2014 po, wala. May certification po yung Office of the Mindanao na wala pong silang nakitang on records ng 2013 and 2014 SAL-Ns,” Batu said said during the interjection of Senator-judge Francis “Kiko” Pangilinan.
But when Pangilinan pressed her to clarify which documents were actually missing, Batu narrowed the gap to Duterte’s 2013 exit SALN.
“Ang nakita lang po namin is for the 2013, wala po siyang exit SAL-N. Pero as to the entry SAL-N, mukhang kompleto naman po. Yung exit SAL-N lang po ng 2013 na ang wala,” she replied. Duterte’s term as Davao City mayor ended on 30 June 2013.
Pangilinan also asked whether the Ombudsman could still accept an exit SALN submitted after the prescribed deadline. “If mag-file po siya ng late, tatanggapin pa rin po namin yun,” Batu said.
“But that would be labeled as a late filing?” Pangilinan asked.
“Yes, Your Honor,” Batu replied.
Republic Act No. 6713 requires public officials to file a SALN upon assumption of office, annually, and within 30 days after separation from government service.
No declaration of cash
The questioning then moved from the availability of Duterte’s SALNs to what she actually declared in them, with Batu asked to identify entries covering cash, shares of stock and business interests.
Batu testified that Duterte’s SALNs contained no separate declaration of cash on hand or cash in bank.
“For SALNs 2021, 2022, 2023, 2024, and 2025, wala pong naka-declare na cash on hand or in bank,” Batu said.
Batu had earlier testified that Duterte likewise declared no cash on hand or cash in bank in her 2019 and 2020 SALNs.
The absence of separate cash entries prompted questions about how the amounts were reported. Duterte’s defense has said her cash on hand, cash in bank and jewelry were included under the “others” category in her SALNs.
That explanation led the court into a more technical question: if cash was included under “others,” how does that affect the ability to verify the declaration?
Cash lumping
Batu explained why cash on hand and cash in bank are significant when examining a public official’s SALN, particularly because bank balances can be independently verified.
“Important din to separate it from yung other assets because yung cash in bank in particular is verifiable,” Batu said. She explained that bank records could be compared against what was declared in a SALN.
Cash is also particularly significant because of its liquidity.
“Yung cash kasi madali pagalawin. And therefore, yung cash in bank and cash on hand — required siya i-declare doon sa SALN,” she said, noting that once money is withdrawn from a bank, it can become difficult to track where it goes.
She cited the requirement to disclose the address of real property as an example of how SALN entries can be independently checked.
“Required na i-disclose mo yung address ng real property mo. Para pwede talaga ma-check kung tama yung ginawa mo sa SALN,” she said.
The same scrutiny over what must be disclosed carried into the court’s next question: whether every type of financial interest is subject to the same disclosure requirements.
Acquisition cost
Presiding officer Francis “Chiz” Escudero pressed Batu on whether the SALN requires public officials to state the acquisition cost of their business interests.
Batu said the business-interest and financial-connections portion of the SALN does not contain an acquisition-cost field.
Escudero then clarified that the absence of an acquisition-cost field applied to the business-interest section, not to personal property.
Batu agreed. “Meron po tayong acquisition cost form para po sa personal properties, Your Honor,” she said.
Under Section 8 of Republic Act No. 6713, or the Code of Conduct and Ethical Standards for Public Officials and Employees, a SALN must contain information on personal property and acquisition cost, as well as all business interests and financial connections.
The prescribed SALN form treats those disclosures separately: personal properties are listed with their acquisition year and “acquisition cost/amount,” while the business-interest section asks for the name of the entity, business address, nature of the interest or financial connection, and the date the interest was acquired.